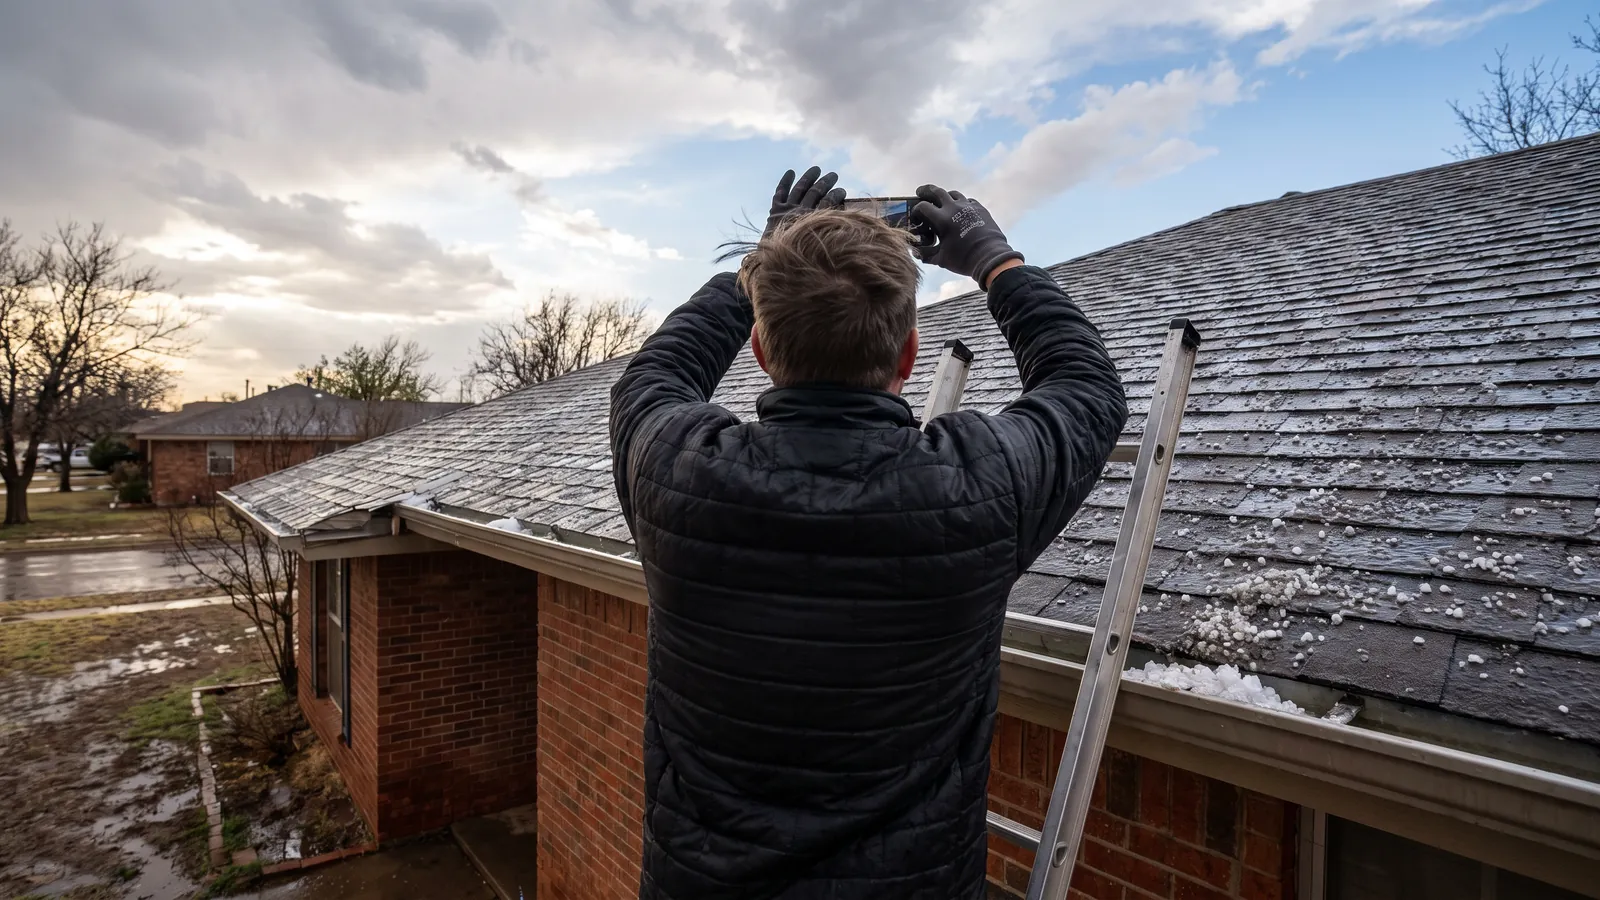
How a hail or wind roof claim usually works in Texas
Every policy is different and only your insurer can decide coverage. This is the general shape of the process, so the steps and words make sense when you are in it.
1. Document and report
Write down the storm date and keep any photos from that day. Read your policy for the wind and hail deductible, which in Texas is often a percentage of the home's insured value rather than a flat dollar amount, and for any time limit on reporting. Many homeowners get a roof inspection first to see whether there is damage worth claiming, then report it to the insurer.
2. The adjuster's inspection
The insurer sends an adjuster, an employee or an independent adjuster working for the company, to inspect the roof. You can have your roofer there. The adjuster writes a scope of loss listing what the insurer believes was damaged by the covered storm and what it will pay to fix it. Read it carefully; it lists squares, materials and line items much like a roofing estimate.
3. Actual cash value and depreciation
Many policies pay a roof claim in two parts. The first check is the actual cash value: the replacement cost minus depreciation for the roof's age, minus your deductible. If your policy pays replacement cost, the withheld depreciation is paid after the work is completed and invoiced. Some policies, especially on older roofs, pay actual cash value only. Your declarations page says which you have.
4. Differences and supplements
If the adjuster's scope misses something, for example damaged vents, required drip edge or decking found during tear-off, the contractor can document it and the insurer may approve a supplement. Disagreements are handled with the insurer; your policy describes the options, which can include an appraisal process.
5. The deductible
The deductible is your share, and you pay it. The Texas Insurance Code does not allow a contractor to pay, waive or rebate it, or to advertise that they will. A contractor who offers to "take care of" the deductible is offering to break the law.
What a contractor can and cannot do
A roofer can inspect, document, write an estimate, meet the adjuster, and do the approved work. A roofer cannot negotiate your claim for you as if they were a public adjuster, cannot promise coverage, and should never ask you to sign over control of your claim. We stay on the roofing side of that line.
Quick answers
Will my premium go up if I file?
That depends on your insurer and history. Ask your agent before filing if you are concerned.
What if the adjuster says there is no damage?
Ask for the findings in writing. You can ask the insurer to reconsider with additional documentation, and your policy lists further options.
Do I have to use the insurer's preferred contractor?
Generally you can choose your own contractor. Check your policy and ask your insurer if unsure.
What is a percentage deductible?
A deductible figured as a percentage of the home's insured value, for example 1 or 2 percent, common for wind and hail in Texas.
Keep reading: Hail damage repair · Hail checklist · Financing